

Walled Gardens Are Closing Ranks — What Google, Meta and Amazon’s AI Ad Stacks Mean for Independent DSPs

For years, the promise of the open internet was built around choice. Advertisers could use independent demand-side platforms (DSPs) to access inventory across publishers, apps, connected TV and emerging digital environments, while agencies could stitch together audiences, supply and measurement across a fragmented media landscape.
That proposition is becoming harder to defend.
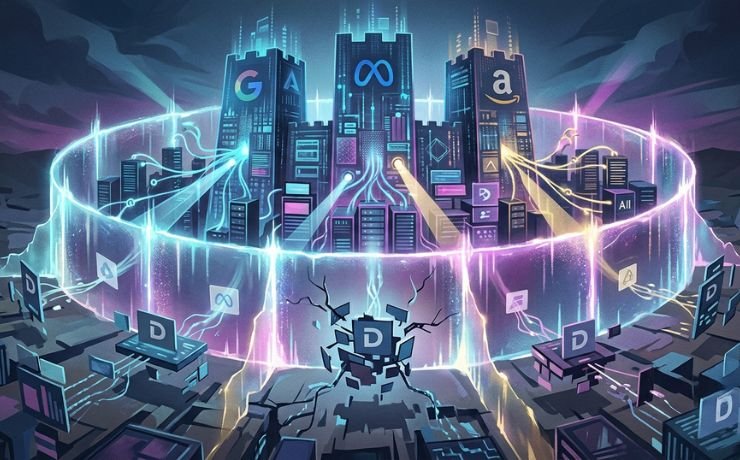
Google, Meta and Amazon are steadily building advertising systems in which media buying, audience intelligence, creative generation, optimisation and measurement sit inside the same technology stack. AI is accelerating that integration. What once required a collection of specialist platforms and human intervention can increasingly be handled within a single ecosystem.
This is not simply another chapter in the automation story. It represents a structural shift in where advertising intelligence lives.
Google’s AI-powered advertising products are moving targeting, creative optimisation and campaign decisions deeper into Google’s own ecosystem. Meta is using increasingly sophisticated AI models to automate campaign setup, creative generation, audience selection and delivery. Amazon has an unusually powerful combination of shopping behaviour, retail media inventory, DSP capabilities and commerce data, and is extending its advertising proposition into newer environments.
The result is a market in which the largest platforms are no longer simply selling media inventory. They are attempting to own the operating system through which advertising decisions are made.
The DSP used to be the control layer
The independent DSP emerged partly because advertisers needed a layer of control between themselves and an increasingly fragmented digital ecosystem. It offered a way to buy audiences across multiple publishers and exchanges, apply data and frequency strategies, optimise bids, manage supply and measure outcomes without having to build a direct relationship with every individual media property.
That role made the DSP strategically important.
But the value proposition changes when the largest media platforms can combine inventory with proprietary signals and machine learning. Google does not need to convince advertisers that its AI can optimise access to Google’s search, YouTube, display and other properties separately. Its increasingly automated campaign products bring multiple Google surfaces into a single campaign environment.
Meta is following a similar trajectory. Its advertising systems are increasingly designed to reduce the number of decisions advertisers need to make manually. AI is being used across targeting, delivery, creative development and campaign optimisation, allowing advertisers to hand more of the media decision-making process to the platform.
Amazon has a different advantage. Its advertising proposition sits close to commerce. The company can connect media exposure with shopping behaviour, product discovery and transaction signals, while Amazon DSP extends that proposition beyond Amazon-owned properties.
Put together, these developments create a difficult question for independent DSPs: if the major platforms can optimise media using more data, more inventory and increasingly capable AI, what remains for the intermediary?
AI makes the walls higher
The important point is that AI does not automatically make walled gardens stronger. But AI becomes particularly powerful when it has access to a large, proprietary stream of behavioural signals.
A model can optimise a campaign only as well as the signals available to it. Google has search intent, YouTube behaviour and its broader advertising ecosystem. Meta has engagement and interaction signals across its social platforms. Amazon has a direct relationship with shopping and transaction activity.
The advantage is not simply having more data. It is having data that can be connected directly to an advertising decision.
This distinction matters.
An independent DSP may know that a user belongs to a particular audience segment, has visited certain types of content or is likely to convert. A walled garden may have a much richer understanding of what that user is doing within its own ecosystem and can feed those signals directly into bidding, ranking, creative selection and measurement.
AI turns that data advantage into an operational advantage.
The platforms are increasingly building systems that can process real-time signals, adjust targeting and creative delivery, identify new audience opportunities and optimise campaigns with limited manual intervention.
That means the optimisation loop is becoming increasingly self-contained: signal goes in, the platform makes a decision, the ad is delivered, the response is measured and the resulting data feeds the next decision.
The fewer external links in that loop, the less essential an independent intermediary becomes.
The creative layer is now part of the media stack
Perhaps the biggest change is that the DSP conversation can no longer be separated from creative.
Historically, media technology and creative technology operated in different parts of the marketing ecosystem. Creative teams developed assets, agencies adapted them for channels and DSPs handled audience and bid decisions.
AI is collapsing those boundaries.
Google’s advertising products can now generate and modify assets, while its automated campaign systems can optimise messaging and creative delivery based on predicted performance. Video and image variations can increasingly be produced within the same ecosystem in which media is being bought.
Meta is moving in a similar direction, with AI-generated images, video, translations, product integrations and other creative capabilities increasingly embedded in its advertising workflow.
This changes the competitive equation for independent DSPs.
If a platform can decide which audience to target, create multiple versions of an ad, determine where to place them and optimise delivery based on the resulting conversion data, the traditional separation between media buying and creative optimisation starts to disappear.
The DSP is no longer competing only against another DSP.
It is competing against a vertically integrated marketing machine.
Amazon’s advantage is particularly different
Amazon’s position deserves separate attention because its data advantage is rooted in commerce rather than simply media consumption.
Retail media has already changed the way marketers think about intent. The valuable signal is no longer only whether somebody clicked an ad or visited a website. It can include what a consumer searched for, what products they considered, what they purchased and how those behaviours relate to advertising exposure.
Amazon can bring several of these signals together inside one commercial ecosystem.
That gives Amazon DSP a proposition that independent DSPs may struggle to replicate. The platform is not simply promising better media buying. It can connect media exposure to a broader commerce journey.
The expansion of advertising into conversational environments could take this further. If consumers increasingly discover products through AI interfaces rather than conventional search, social feeds or retail websites, the battle for advertising technology will move into those interfaces too.
And the companies that already control consumer intent, commerce data and advertising infrastructure will enter that market with a significant starting advantage.
So where does that leave independent DSPs?
It would be easy to conclude that independent DSPs are simply being squeezed out. The market is more complicated than that.
There is still a fundamental reason for an independent layer: advertisers do not operate in one ecosystem.
A large consumer brand may need Google for Search and YouTube, Meta for social, Amazon for commerce, retail media networks for shopper audiences, connected TV for incremental reach, premium publishers for context and independent platforms for access to the broader open web.
The problem is that these environments increasingly operate as separate data and measurement islands.
That fragmentation creates a new opportunity for independent technology companies, but it is a different opportunity from the one that existed a decade ago.
The independent DSP of the future may have less value as a simple buying engine and more value as an orchestration layer.
It could help advertisers understand how audiences overlap across platforms, manage frequency across environments, bring together measurement signals, optimise open-web supply and provide a consistent layer of governance across different media ecosystems.
That is a harder proposition to build, but potentially a more defensible one.
Transparency becomes a competitive product
There is another factor working in favour of independent players: advertisers still need to understand what is happening inside their media investment.
Automation can improve efficiency, but it can also reduce visibility.
When targeting, bidding, creative selection and optimisation are handled by algorithms, marketers can end up with fewer levers to pull and less clarity around why a campaign made a particular decision.
This is becoming a broader industry concern as advertising becomes increasingly fragmented across walled gardens, retail media networks and independent platforms.
Independent technology can play a role here by providing measurement, verification, identity resolution, supply-path analysis and cross-platform intelligence that individual walled gardens cannot provide neutrally.
That neutrality could become more valuable as media buying becomes more automated.
In other words, the independent DSP may not win by having the smartest algorithm in the market. It may win by helping advertisers understand and govern the algorithms they are already using.
The open internet still has one important advantage
For all the momentum behind walled gardens, the open internet is not disappearing.
It remains where a significant amount of premium content, publisher journalism, specialist communities, streaming inventory and contextual environments live. The challenge has been making that inventory as easy to buy, understand and optimise as inventory inside closed ecosystems.
AI could actually help solve part of that problem.
Better contextual understanding can make it easier for advertisers to evaluate pages and environments without relying entirely on user-level identity. Better models can classify content, predict attention and understand the relationship between creative and context.
That could make contextual advertising more sophisticated rather than turning it into a fallback for a post-cookie world.
The open internet therefore does not necessarily need to imitate a walled garden. Its opportunity may be to become better at using context, attention, quality and transparency as signals.
The regulatory question will matter too
There is also a larger structural question hanging over the market: how much control should one company have over the technology, data and inventory involved in an advertising transaction?
As advertising platforms become more vertically integrated, regulators and industry participants will continue to examine whether the efficiencies created by integration also create risks around competition, transparency and market access.
The significance extends beyond any one company.
For advertisers, publishers and technology companies, the question is not simply whether an integrated stack works. It is also whether the market retains enough choice for participants to challenge how that stack operates.
The next battle is over the operating system for advertising
The old ad-tech battle was about who could buy the most impressions efficiently.
The new battle is about who can make the most advertising decisions.
That includes deciding which consumer matters, which signal should be trusted, which creative should be shown, which inventory should be purchased, how much should be paid, whether the user converted and what the system should learn from that outcome.
Google, Meta and Amazon are increasingly bringing those decisions inside their own ecosystems.
That does not make independent DSPs obsolete. But it does make their old positioning less compelling.
The independent platform that simply promises another way to buy programmatic inventory will find the market increasingly difficult. The platform that can offer cross-platform intelligence, transparent measurement, high-quality supply, privacy-conscious data collaboration and genuine control may have a more durable role.
The distinction is subtle but important.
Advertisers do not necessarily need another wall. They need a way to navigate the walls that already exist.
That may ultimately be the strongest case for independent ad tech in the AI era: not competing with every walled garden on its own terms, but providing the connective tissue between them.
Because as AI makes each individual advertising ecosystem smarter, the industry’s biggest unresolved problem may become less about optimisation within a platform and more about what happens between platforms.
And that is precisely where the next generation of independent DSPs will have to prove their value.